California homeowners across the San Francisco Bay Area continue to reap substantial financial relief from Proposition 13, the state's landmark property tax limitation law. However, an analysis of regional real estate figures shows that in numerous communities, the financial cushion provided by the measure has noticeably contracted over recent years. While residents still collectively save significant sums of money, the difference between actual market prices and taxable assessments has grown tighter in a majority of local counties.
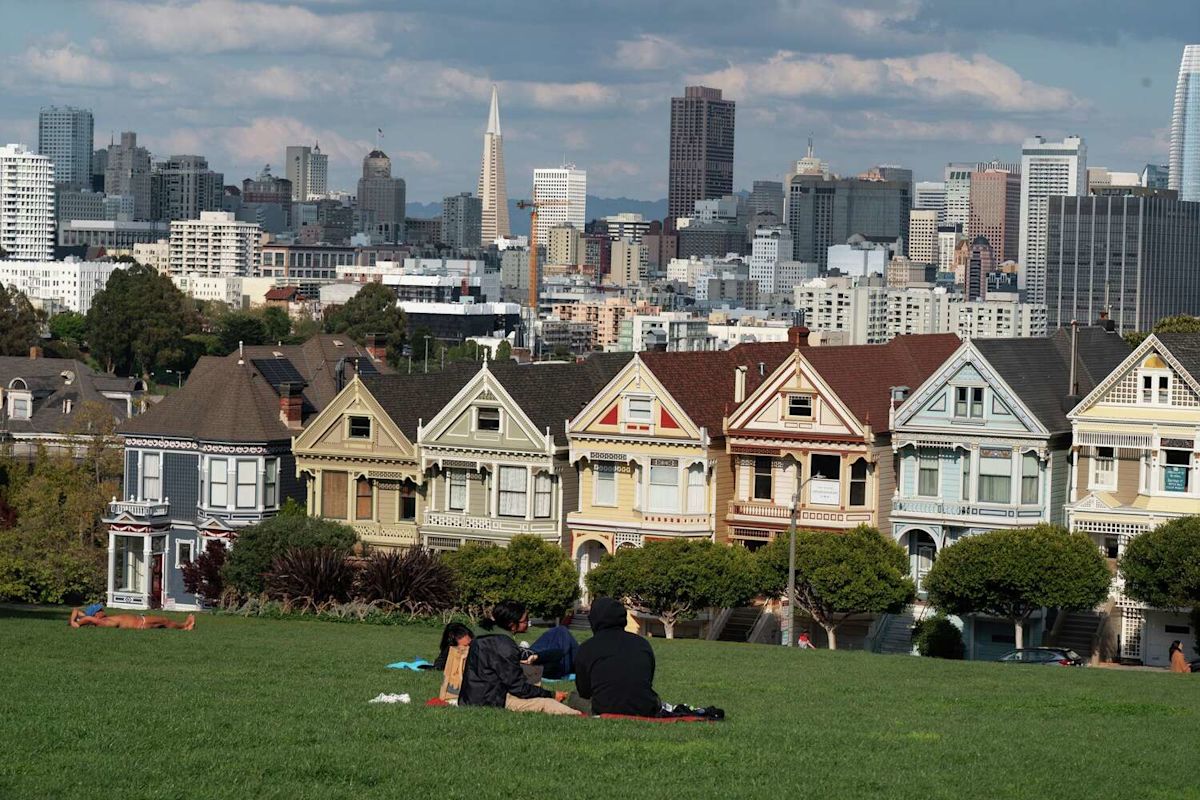
In San Francisco, for instance, the landmark law delivered an estimated average tax reduction of roughly $9,000 per homeowner in 2025, based on a San Francisco Chronicle evaluation of property figures from real estate brokerage Redfin. During that year, the typical residential property in the city commanded a market valuation approaching $1.6 million. In contrast, the average taxable assessed value utilized by public assessors to calculate annual tax obligations stood at just over $1 million.
This disparity meant that the typical San Francisco residence was worth approximately 52% more on the open market than its recorded value on the municipal tax rolls. Although that tax buffer remains significant, it represents a substantial decline from 2017, the earliest year for which reliable comparative data was compiled. Back in 2017, market valuations across San Francisco were more than double the corresponding assessed figures, indicating a much wider tax shelter for property owners at that time.
The contraction of this tax relief margin is not unique to San Francisco. Across six of the nine counties comprising the greater Bay Area, the spread separating typical market prices from their corresponding assessed valuations narrowed between 2017 and 2025. While complete property tax roll data for 2026 was not yet accessible at the time of the review, recent sharp increases in San Francisco home valuations suggest that the pricing gap may once again be expanding.
The broader statewide trajectory mirrors this regional compression. In virtually every California county included in the real estate dataset, assessed valuations expanded at a faster pace than prevailing market prices between 2017 and 2025. Consequently, local governments have been levying taxes on an increasingly larger share of residential properties' total estimated market worth.
Enacted by voters in 1978, Proposition 13 fundamentally altered California's municipal finance system by establishing a baseline property tax rate capped at 1% of a home's purchase price, supplemented by local voter-sanctioned tax assessments. Crucially, the measure restricts annual increases in a property's assessed value to a maximum of 2%, provided the home does not change ownership. This framework ensures that long-term owners experience substantial tax discounts as fair-market real estate prices escalate over time.
Despite the broader regional contraction in savings, certain high-value communities bucked the trend. In Santa Clara County's city of Cupertino, the valuation divergence expanded substantially over the eight-year evaluation period, growing from $1.2 million in 2017 to $1.5 million by 2025. This expanding margin allowed Cupertino homeowners to reduce their annual property tax payments by an average of more than $29,000 in 2025.
Nonetheless, across Santa Clara County as a whole, assessments generally gained ground against market valuations. In 2017, the average assessed property value across the county hovered around $640,000, representing roughly 46% of the prevailing $1.4 million market average. By 2025, typical assessed figures climbed to nearly $1.1 million, which accounted for approximately 57% of the county's $1.9 million average market price.
Real estate analysts observe that the gap separating assessed valuations from open-market figures functions much like an accordion, naturally stretching apart during sharp economic expansions and compressing during market shifts. Michael Lane, state policy director at the regional think tank SPUR, noted that home valuations accelerated rapidly during the prolonged recovery following the Great Recession, a boom that gained even more momentum during the early stages of the coronavirus pandemic.
Lane explained that during the pandemic era, historically low mortgage interest rates combined with the widespread adoption of remote work spurred robust homebuying activity throughout the region. However, this surge in property transactions had an important tax consequence: whenever residential real estate changes hands, the property is automatically reassessed at its current full market valuation. This turnover wave elevated aggregate assessed values and brought them significantly closer to prevailing market levels.
That rapid cycle of sales and subsequent reassessments eventually encountered headwinds. As Lane pointed out, the housing market dynamic shifted dramatically in 2022 when mortgage interest rates surged. The sudden increase in borrowing costs caused regional property sales to dry up, halting the high volume of transfers that had previously reset assessments to current market peaks.
While the tax-capping legislation maintains enduring popularity among the state's electorate, it continues to spark debate among economists and housing analysts regarding its broader economic impacts. Sarah Karlinsky, director of research and policy at the UC Berkeley Terner Center for Housing Innovation, highlighted that the current structure generates distinct market distortions.
According to Karlinsky, keeping property assessments artificially low for long-standing owners ultimately places a heavier fiscal load on newer homeowners. These recent buyers must shoulder a disproportionate tax burden to compensate for the municipal revenue gaps created when longer-tenured households pay taxes based on dated, suppressed property valuations.
Housing specialists further contend that the tax protections discourage aging Californians from downsizing from expansive family properties they no longer fully utilize. This dynamic restricts housing turnover, suppresses overall listing inventory, and intensifies competition among prospective buyers searching for available homes in an already constrained market.
In an attempt to address some of these market frictions, California implemented a reform measure in 2021 that permits eligible older homeowners to transfer their accumulated Proposition 13 tax protections to a new primary residence when they decide to relocate.
Ultimately, despite the relative narrowing of tax savings in San Francisco and five other Bay Area counties between 2017 and 2025, Proposition 13 remains a cornerstone of the state's property landscape. As real estate cycles continue to evolve and local prices experience renewed momentum, the financial buffer provided by the 1978 measure will continue to shape household finances and regional housing dynamics for years to come.



(0)